

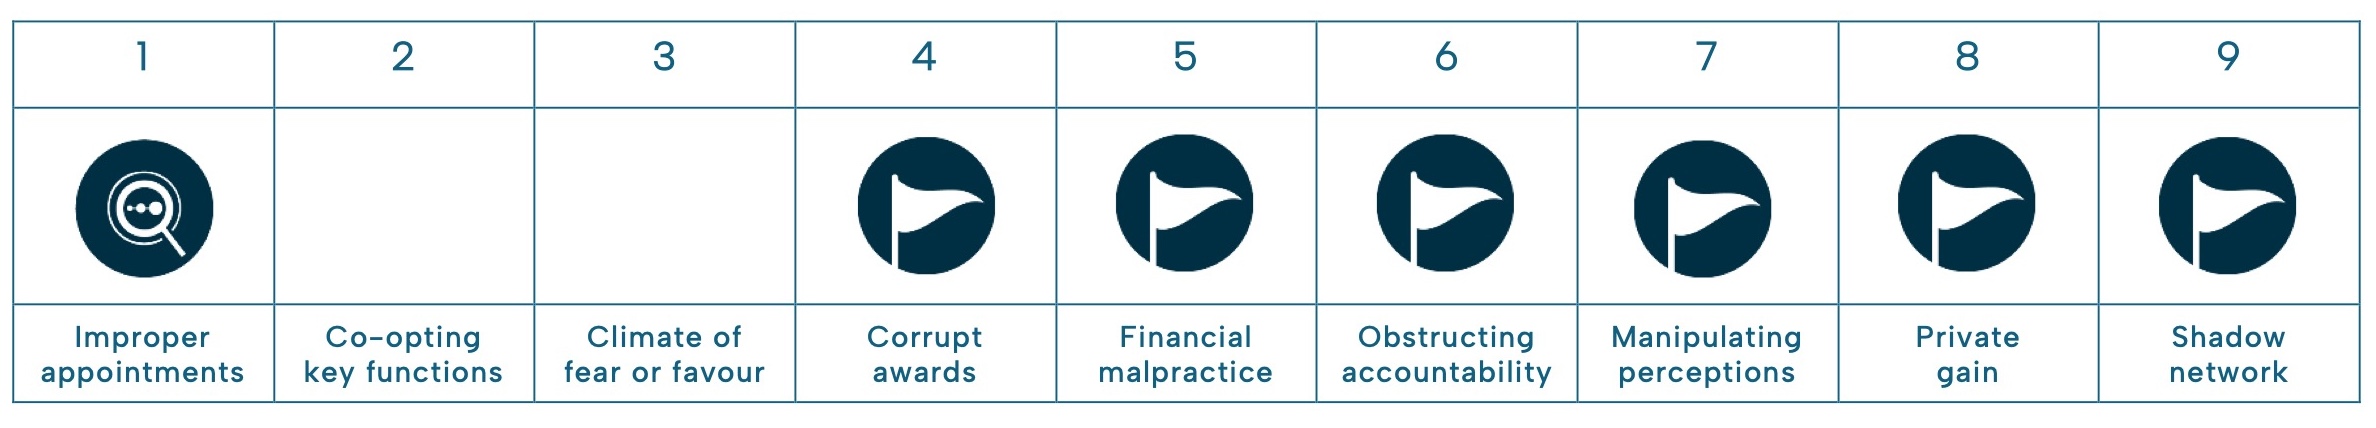
• ACTis has raised six flags for Ithala Bank and placed one under monitoring.
• Corporate governance, prudential compliance and financial risk management at Ithala Bank have deteriorated under the oversight and management of its leadership. This is despite the South African Reserve Bank (SARB) highlighting problems and insisting that they be addressed. Ithala Bank is reportedly insolvent, the deposit and loan businesses have been dismantled, and it has lost customers.
• Yet, many in the Bank’s leadership benefited from preferential loans. These personal gains conflict with the obligation to protect the public interest.
• Rather than driving urgent reform and accountability, those responsible for Ithala Bank took a defensive and evasive stance. An alternative narrative sought to frame the Bank and its leadership as innocent of wrongdoing, claiming that the Bank’s operational problems stemmed from actions by financial authorities.
• It is a positive development that this stance has recently changed, with the provincial government acknowledging failures in governance and fiduciary duty. While the resignation of the Ithala Bank Board could mark the start of reform, no one has been held responsible for the Bank’s demise. Further investigation is required to expose the full extent of what has taken place, and consequence management is required to restore accountability. Reforming the Bank’s operating model and governance practices is central to re-establishing a sustainable institution.
• The costs of Ithala’s failure have been borne by the National Treasury and by the poorer communities and small businesses of KZN.
o The National Treasury had to step in to reimburse Ithala Bank depositors the R2.2bn owed to them.
o Ithala Bank’s client base includes approximately 257,000 depositors and 65,000 South African Social Security Agency grant recipients. In many rural communities, Ithala is the only available bank. Throughout 2025, numerous reports emerged of communities and small businesses (including burial societies and services that provide meals to schools) struggling to access funds and of individuals not receiving their social security grant payments. In 2024, Ithala Bank provided micro-lending of R737.5m to formal and informal businesses, some of which could not provide the credit history or collateral that other banks require. If the current client base – which includes low-income households, small businesses, taxi associations, cooperatives, stokvels and emerging farmers – is no longer able to access these banking services, KZN may face negative economic consequences.